Building your empire one loan at a time.
Your Premier Lender
Miami Mortgage Loan Officer Serving All of Florida
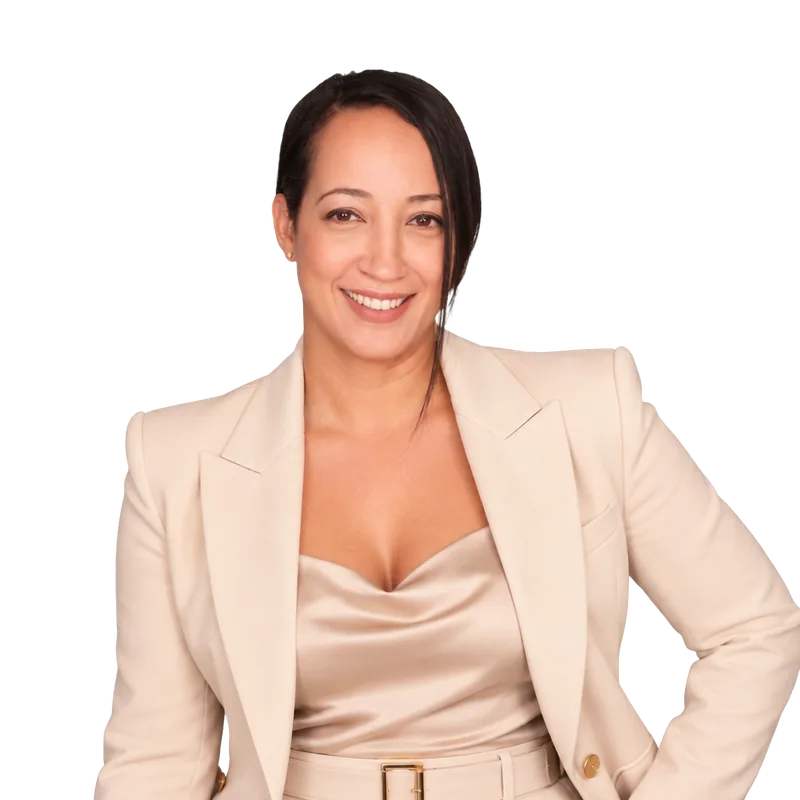
Jennyffer Kurz
Loan Officer | NMLS #1844447 | Bold Mortgage NMLS #75243
Your premier lending partner at Bold Mortgage, serving Miami and every city in Florida. FHA, VA, conventional, jumbo, USDA and refinance home loans — from first homes to jumbo financing, I make the path to your keys clear, fast, and calm.
About Jennyffer
A trusted Miami mortgage professional serving all of Florida
Based in Miami and licensed throughout Florida, Jennyffer Kurz brings deep expertise across the full spectrum of home loan programs — conventional, FHA, VA, USDA, jumbo, HELOC, renovation, reverse, and Non-QM financing, plus rate-and-term and cash-out refinancing — paired with the kind of attentive service that keeps clients and real estate professionals coming back.
Her approach is simple: listen first, explain clearly, and move quickly. Clients get a candid read on their options, a plan that fits their finances, and a mortgage partner committed to exceeding expectations at every step — pre-approval, house hunting in Miami-Dade, Broward, Palm Beach or anywhere in Florida, underwriting, rate lock, and closing.
Personalized guidance
Every borrower is different. Your loan strategy is built around your goals, timeline, and comfort level.
Fast, accurate advice
Straight answers when you need them, so you can make offers and decisions with confidence.
Through every step
From pre-approval to the closing table, you'll always know exactly where your loan stands.
Compare
Florida loan programs at a glance
| Program | Minimum down payment | Mortgage insurance | Best for |
|---|---|---|---|
| FHA | 3.5% | Upfront + annual MIP | Flexible credit, smaller down payment |
| VA | $0 (eligible borrowers) | None monthly; funding fee may apply | Veterans & service members |
| Conventional | 3% (qualifying buyers) | PMI under 20% down, removable | Solid credit, second homes |
| Jumbo | Often 10%–20% | Usually none | Loans above conforming limits |
| USDA | $0 (eligible areas) | Upfront + annual guarantee fee | Rural/suburban buyers within income limits |
| First-Time Buyer | 0%–3.5% + possible assistance | Depends on loan type | First-time buyers with limited savings |
| DSCR | Often 20%–25% | None | Rental property investors |
| Bank Statement | Often 10%+ | None | Self-employed borrowers |
General guidelines only; eligibility, terms, and requirements vary by borrower and property.
Loan Programs
The right program, matched to your situation
FHA Loans
An FHA loan is a mortgage insured by the Federal Housing Administration. It allows down payments as low as 3.5% for borrowers with a credit score of roughly 580 or higher and more flexible guidelines than many conventional loans. It requires upfront and annual mortgage insurance premiums and is for primary residences only.
VA Loans
A VA loan is a mortgage guaranteed by the U.S. Department of Veterans Affairs for eligible service members, veterans, and some surviving spouses. Eligible borrowers can buy with $0 down and pay no monthly mortgage insurance. A one-time VA funding fee usually applies unless you are exempt, such as for a service-connected disability.
Conventional Loans
A conventional loan is a mortgage not insured by a government agency, typically following Fannie Mae and Freddie Mac guidelines. Qualifying first-time buyers may put as little as 3% down. Private mortgage insurance is required under 20% down and can usually be removed later. Conventional loans also work for second homes and investment properties.
Jumbo Loans
A jumbo loan finances an amount above the conforming loan limit set by FHFA for your county. Jumbo loans are common in Florida luxury markets and typically require stronger credit, larger down payments, and more cash reserves. Programs vary by investor, including options for self-employed and high-net-worth borrowers.
USDA Loans
A USDA Guaranteed loan helps low- and moderate-income buyers purchase homes in eligible rural and suburban areas with $0 down. Household income must fall within USDA limits for the county, and the home must be a primary residence. The program charges an upfront and annual guarantee fee instead of traditional mortgage insurance.
First-Time Homebuyer & Down Payment Assistance
Florida first-time buyers can combine low down payment loans — FHA at 3.5%, conventional at 3% for qualifying buyers, or VA and USDA at $0 down for eligible borrowers — with state and local down payment assistance programs. Most assistance has income and price limits and requires homebuyer education.
Refinance
Refinancing replaces your current mortgage with a new one. A rate-and-term refinance can change your payment, shorten your term, or remove mortgage insurance. A cash-out refinance lets you borrow against your equity for renovations, debt consolidation, or other goals. The right choice depends on costs, timing, and how long you'll stay.
DSCR Investor Loans
A DSCR (debt service coverage ratio) loan is a Non-QM investment property loan that qualifies you based on the property's rental income compared to its monthly housing costs, rather than your personal income. It's designed for investors buying or refinancing rentals and typically requires a larger down payment and reserves.
Bank Statement / Self-Employed Loans
A bank statement loan is a Non-QM mortgage that lets self-employed borrowers qualify using 12 or 24 months of personal or business bank deposits instead of tax returns. It helps business owners whose write-offs lower their taxable income. Expect larger down payments and different pricing than conventional loans.
Non-QM Loans
Non-QM (non-qualified mortgage) loans serve borrowers whose income, property, or credit doesn't fit agency guidelines. Options include bank statement, DSCR, asset depletion, and loans for non-warrantable condos or recent credit events. They still require verifying ability to repay, typically with larger down payments.
Condo Financing
Financing a Florida condo means qualifying both you and the building. Lenders review the association's budget, reserves, insurance, litigation, investor concentration, and structural safety requirements. Warrantable condos can use conventional, FHA, or VA loans; non-warrantable condos may need Non-QM or portfolio financing.
HELOC
A HELOC is a revolving line of credit secured by your home's equity, usually in second position behind your existing mortgage. You draw funds as needed during a draw period, then repay. It lets you keep your current first mortgage in place. Availability and terms depend on eligibility, underwriting, and Bold Mortgage program guidelines.
FHA 203(k) Renovation Loans
An FHA 203(k) loan lets you finance the purchase (or refinance) of a home plus the cost of repairs or renovations in one mortgage, with as little as 3.5% down for qualifying borrowers. Limited 203(k) covers smaller non-structural projects; Standard 203(k) covers larger work with a HUD consultant. Availability and terms depend on eligibility, underwriting, and Bold Mortgage program guidelines.
Reverse Mortgages
A reverse mortgage, most commonly the FHA-insured HECM, lets homeowners 62 and older convert part of their home equity into cash without a required monthly mortgage payment. You keep title and must live in the home, pay property taxes and insurance, and maintain it. HUD-approved counseling is required. Availability and terms depend on eligibility, underwriting, and Bold Mortgage program guidelines.
Down Payment Assistance Program Florida
Florida down payment assistance may help eligible homebuyers with upfront purchase costs. Explore Miami-Dade County, Broward County, and Florida Housing options below. Each program has its own eligibility, education, funding, and repayment requirements. County approval, mortgage underwriting, and confirmation of lender participation are required before relying on assistance.
Payment Calculator
Run the numbers in seconds
Estimated monthly payment
—
Enter an interest rate to see your estimate. Ask Jennyffer for a current personalized quote.
Loan amount $400,000
- Principal & interest
- —
Estimates only. Taxes and insurance are approximated at 1.1% and 0.45% of home price annually. Actual figures vary by property, county, and credit profile.
Get a Personalized QuoteVA Loans & Military Families
Proud Marine wife, serving those who serve
Jennyffer Kurz is the wife of a United States Marine. Living the military life — the deployments, the moves, the paperwork — is exactly why helping service members and veterans use their VA home loan benefit is the most meaningful part of her work. She has seen firsthand how many military families never realize the full value of the benefit they earned, and she makes sure hers never leave it on the table.
She works with active duty, Reserve, National Guard, retired, and surviving spouse borrowers from every branch of service — Marine Corps, Army, Navy, Air Force, Space Force, and Coast Guard — buying and refinancing homes in Miami, Jacksonville, Tampa, Pensacola, Orlando, and across the state of Florida, near bases and installations statewide.
- U.S. Marine Corps
- U.S. Army
- U.S. Navy
- U.S. Air Force
- U.S. Space Force
- U.S. Coast Guard
- National Guard
- Reserves
$0 down payment
Eligible veterans and active-duty service members can finance up to 100% of the purchase price on a Florida home.
No monthly PMI
VA loans skip private mortgage insurance entirely, which keeps the monthly payment lower than FHA or conventional financing.
COE & entitlement help
Guidance on your Certificate of Eligibility, entitlement restoration, VA IRRRL refinances, and Florida VA loan limits.
Where I lend
Mortgage lending in Miami and all of Florida
Local mortgage guidance across Miami-Dade, Broward, Palm Beach, and all of Florida.
Getting Started
Three simple steps
Answer a few questions
Share your goals, timeline, and basic financials — it takes just a few minutes.
Get matched with the right program
Jennyffer compares your options and recommends the loan that fits best.
Lock in your rate
Secure your terms and move confidently toward the closing table.
Apply in minutes
Start your application today and get a clear answer on what you qualify for.
Guides
Latest guides
Mortgage Rates Passed 7%: What Florida Buyers Should Know
Freddie Mac's 30-year average topped 7% again. Here's what that means, and doesn't mean, for Florida homebuyers getting a quote today.
Refinance vs. Cash-Out: Sorting Out Your Options in Florida
Florida homeowners comparing rate-and-term refinance, cash-out refinance, and VA IRRRL options as rates move. Learn the break-even math before you decide.
Fannie Mae's 2026 Condo Rule Changes for Florida Buyers
Fannie Mae's Lender Letter LL-2026-03 retires Limited Review and PERS for Florida condos. Here's what changes for buyers and what to ask your lender.
FAQ
Good questions, clear answers
How do I get pre-approved for a mortgage in Miami or anywhere in Florida?
Start by applying online or calling (305) 401-2778. Jennyffer Kurz reviews your income, assets, and credit to determine whether you qualify for pre-approval, subject to underwriting. Because she is licensed statewide, the same process works in Miami, Fort Lauderdale, Orlando, Tampa, Jacksonville, Naples, or any other Florida city.
What is an FHA loan and who qualifies in Florida?
An FHA loan is insured by the Federal Housing Administration and allows down payments as low as 3.5% with more flexible credit guidelines. It is popular with first-time buyers. FHA loans carry an upfront and annual mortgage insurance premium (MIP).
What is a VA loan and how do Florida veterans use it?
A VA loan is guaranteed by the Department of Veterans Affairs for eligible service members, veterans, and surviving spouses. It allows $0 down for eligible borrowers and has no monthly mortgage insurance; a one-time VA funding fee may apply unless exempt.
What is PMI?
Private mortgage insurance (PMI) protects the lender if a borrower stops making payments. It is generally required on conventional loans with less than 20% down and can usually be removed once you reach 20% equity.
When should I refinance?
Refinancing can make sense when market conditions improve, your credit or income has improved, you want to shorten your term, remove mortgage insurance, or access equity. The right answer depends on how long you plan to keep the home and how quickly savings offset closing costs.
How much do I need for a down payment?
It depends on the loan program and your situation. FHA allows as little as 3.5% down for qualifying borrowers, some conventional programs allow less than 20% down with PMI, and VA loans allow $0 down for eligible borrowers. Down payment assistance may also be available, subject to program rules and funding.
What credit score do I need to buy a home?
Minimums vary by loan program and are set by program guidelines and underwriting. Government-backed loans such as FHA are often more flexible than conventional or jumbo loans. Jennyffer can review your credit and explain which programs may fit.
How long does it take to close on a home?
Timelines depend on the property, the loan program, appraisal and title work, and how quickly documents come in. Condos can take longer when the building needs a project review. Getting pre-approved and gathering documents early helps keep things moving.
What are closing costs?
Closing costs are the fees and prepaid items due at closing, such as lender fees, appraisal, title and settlement charges, recording fees, and prepaid taxes and insurance. The amount depends on the loan and property. You receive a Loan Estimate early in the process and a Closing Disclosure before closing that itemize them.
Can I finance a condo in Florida?
Often, yes, but the building must meet the lender's and the loan program's project requirements in addition to your own approval. Expect a condo questionnaire and a review of the association's budget, reserves, insurance, and inspection status.
What is a jumbo loan?
A jumbo loan is a mortgage above the conforming loan limit for the county. Jumbo loans usually carry stricter credit, reserve, and documentation requirements, subject to underwriting.
Can I get a mortgage if I'm self-employed?
Yes. Self-employed borrowers may qualify with tax returns under standard programs, or with bank statements under alternative documentation programs. Requirements depend on the program and are subject to underwriting.
Contact
Let's get you started
Tell me a little about your goals and I'll follow up personally with next steps.
For Real Estate Professionals
Real Estate Partnership Program (REPP)
General information about employment opportunities with Bold Mortgage for licensed real estate professionals.
This is not an offer of employment or a guarantee of income. Employees are paid through payroll for assigned duties performed under supervision. Not available in Louisiana, North Dakota, Rhode Island, Utah, or West Virginia.
Request REPP Information